Curve fit models
There are several different models available for curve fitting. The various models are briefly explained here.
See also Lines and curves.
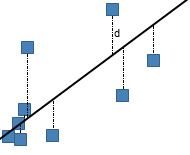
Straight line

where a is the intercept and b is the slope.
Logarithmic

where
a and
b are constants and
ln is the natural logarithm function. This model requires that
x>0 for all data points. Spotfire uses a nonlinear
regression method for this calculation. This will result in better accuracy of
the calculation compared to using linear regression on transformed values only.
Exponential

where a and b are constants, and e is the base of the natural logarithm.
Exponential models are commonly used in biological applications, for example, for exponential growth of bacteria. Spotfire uses a nonlinear regression method for this calculation. This will result in better accuracy of the calculation compared to using linear regression on transformed values only.
Power

where a and b are constants. This model requires that x>0 for all data points, and either that all y>0 or all y<0. Spotfire uses a nonlinear regression method for this calculation. This will result in better accuracy of the calculation compared to using linear regression on transformed values only.
Logistic regression
The logistic regression fit is a dose response ("IC50") model, also known as sigmoidal dose response. The four parameter logistic model is the most important one.
Dose-response curves describe the relationship between response to drug treatment and drug dose or concentration. These types of curves are often semi-logarithmic, with log (drug concentration) on the X-axis. On the Y-axis, you can show measurements of enzyme activity, accumulation of an intracellular second messenger or measurements of heart rate or muscle contraction.
Log10-transformed X-values
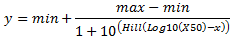
The LoggedX50 value is interpreted as the Log10(X50). For example, if the H30+ concentration at IC50 has a pH of 3, then the LoggedX50 = -3.
Non-logarithmic X-values
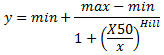
x>0 for all data points and that you use at least
four records to calculate the curve.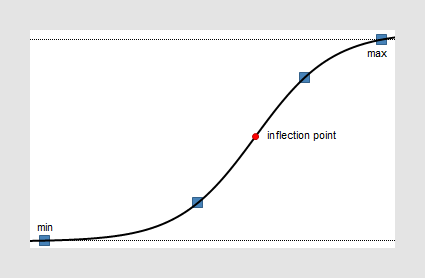
Polynomial
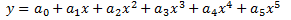
where a0, a1, a2, etc., are constants. The default order is a 2nd order polynomial, but you can change the degree in the settings for the curve. This model requires that you use at least three markers to calculate the curve for a 2nd order polynomial model, and four markers for a 3rd order polynomial, and so on.
If you have a low number of unique x-values, a polynomial curve can be calculated in an unlimited number of ways. This means that you might end up with a curve that does not look as expected. If this happens, you probably should not apply this model to your data.
Some of the models have been partially solved by using the LAPACK software package, see References.
Gaussian
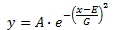
where A is the amplitude (height) of the curve, E is the position of the center of the curve and G is the width.
In Spotfire, you have the possibility to let the application calculate values on the parameters A, E and G automatically from the available data by leaving the curve parameter fields blank. You can also specify one or more of the parameters yourself.
Holt-Winters forecast
The Holt-Winters Forecast uses Spotfire Enterprise Runtime for R (a/k/a TERR™) to compute the Holt-Winters filtering of a time series or anything that can be coerced to a time series. This is an exponentially weighted moving average filter of the level, trend, and seasonal components of a time series. The smoothing parameters are chosen to minimize the sum of the squared one-step ahead prediction errors.
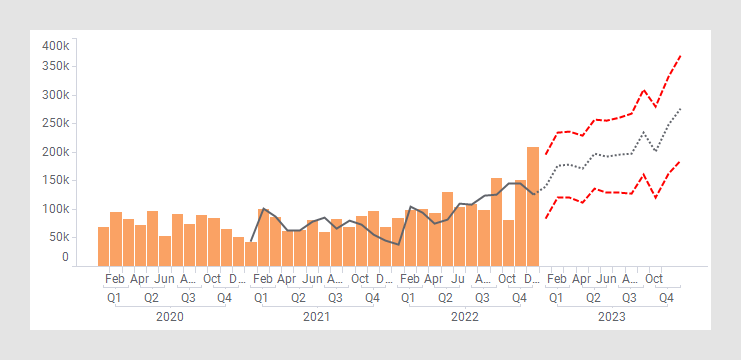
The output of a Holt-Winters Forecast is three different curves: a fitted curve showing the general variation of the measure of interest, a forecast curve predicting the future trend and a confidence interval showing how the insecurity increases the further away from the known values the prediction reaches.
- Level
(alpha) – Specifies how to smooth the level component of the time
series.
The level (alpha) parameter must be larger than 0 but not larger than 1.
A small value means that older values in the X direction are weighted more heavily.
Values near 1.0 mean that the latest value has more weight.
-
Trend (beta) – Specifies how to smooth the
trend component of the time series.
The trend (beta) parameter must be in the interval of 0-1.
A small value means that older values in X direction are weighted more heavily.
Values near 1.0 mean that the latest value has more weight.
- Seasonal
(gamma) – Specifies how to smooth the seasonal component of the
time series.
The seasonal (gamma) parameter must be in the interval of 0-1.
A small value means that older values in X direction are weighted more heavily.
Values near 1.0 mean that the latest value has more weight.
Use the drop-down list to specify how the seasonal component should interact with the other components:
Additive (default) indicates that X is modeled as level + trend + seasonal.
Multiplicative indicates the model is (level + trend) * seasonal.
-
Frequency – Only applicable when a Seasonal
(gamma) component is included in the model.
Specifies the number of seasonal periods to use to compute start values, that is, the number of observations per sampling period. For example, monthly data have a frequency of 12. The frequency must be greater than 1 to fit a seasonal component.
- Time points
ahead – Specifies the number of time points (nodes) into the future
at which to predict the values of the time series.
If the visualization shows months, then the time points ahead equals the number of months forward to predict. If the visualization shows years, then the time points ahead represents the number of years forward to predict.
- Confidence level – Specifies the confidence level. This should be a number larger than 0 but not larger than 1.
- Allow replacement of empty values – Allows you to replace empty values by interpolating the adjacent values. Note that two missing data points in a row cannot be interpolated.
You can specify a frequency or the time points ahead, either using a fixed number or by using a property value, selected using the Set from Property functionality. The property value can in turn be changed by adding a property control in a text area. See Using document, data table or column properties in the analysis and the following topics for more information about properties and property controls.
The used parameters can be shown in labels or tooltips.
Arps decline curve
The Arps decline curve (including the modified Arps decline curve) is a model used within the Energy sector to evaluate how much a well can produce in the future. It can be used to forecast the production of the well, and the remaining reserves, if a well has reached the Boundary dominated flow state. Typically, you use it in a visualization with time on the X-axis and production rate (Barrels per day for oil, or Thousand Cubic Feet per day for gas) on the Y-axis.
This option is available using any Spotfire client, if you have the Spotfire Industry Pro license.
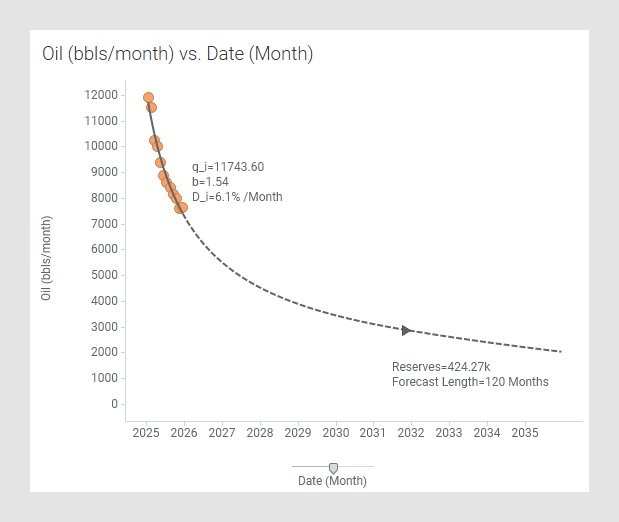
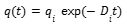 when b=0, known as
exponential decline
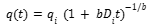 when b not equals 0, known
as hyperbolic decline
In Spotfire, you can optionally specify a decline limit, and in that case, the modified Arps decline curve is used, where the production is assumed to consist of two segments. In the first segment, a hyperbolic decline with a non-zero decline exponent b is used, and in the second segment, exponential decline is used.
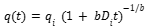 hyperbolic decline for t
< tT
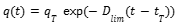 exponential decline for t
> tT
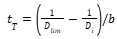
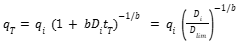
The Arps decline curve fit finds parameters that minimize the least squared sum. However, note that values that are zero or negative are excluded from the sum. Unlike other curve fit models in Spotfire, the Arps decline curve minimizes the squared sum with regard to the original values, no matter if a log scale has been applied to the X-axis or Y-axis.
When defining an Arps decline curve, you can specify the Arps parameters qi, b and Di, as well as the following:
- Time
unit – This option can only be configured when the X-axis is a Date
or DateTime. If the X-axis is a date hierarchy, then this option is
automatically set to the selected hierarchy level. If the X-axis is a Real or
an Integer, then this option is not available and it is up to you to make sure
that the units of the parameters are consistent.
Used for the interpretation of parameter values and the calculation of reserves. Available options are Day, Month and Year.
It is expected that the Y-axis represents the production rate in this unit of time (per day, per month or per year). An incorrect configuration will lead to the wrong calculated reserves.
The parameters are specified and fitted in this unit of time: qi production per day/per month/per year, Di per day/per month/per year.
- Decline limit
for transition to exponential – Specifies the limiting decline
after which the decline should switch from hyperbolic to exponential. The
limiting decline should be specified in the given time unit (per
day/month/year).
If this value is left unspecified, the ordinary Arps model will be used.
- Forecast
length – Specifies that a forecast should be made by extrapolating
the fitted curve past the last data point for the specified amount of time. The
production during the forecast period is summed and presented as reserves. The
forecast can be specified in two modes:
Forecast time - A fixed time in the given time unit (days/months/years).
Economic limit - The forecast ends when the production reaches this limiting value (in production per day/month/year).
You can use the Start at last break check box to specify whether the fit should minimize the least squared sum for all points in the filtering (and optionally marking, if the "Limit to marked data" option is selected), or only the points occurring after the last break in production (the last zero value on the Y-axis).
When exporting the curve data to file or analysis, the following columns are included:
- q_i - The fitted or fixed value of the initial production rate in the given unit of time.
- b - The fitted or fixed value of the decline exponent.
- D_i - The fitted or fixed value of the initial decline rate in the given unit of time.
- D_lim - The limiting decline marking the transition from a hyperbolic to an exponential curve in the Modified Arps model, or null if the Standard Arps model is used.
- q_ecl - The value of the production rate at the end of the forecast period.
- Reserves - The total production during the forecast period.
- Forecast length - The length of the forecast in the given unit of time.
- Time Unit - The given unit of time "Day", "Month", or "Year" if the X-axis is a Date, DateTime or a date hierarchy . "Unknown" otherwise.
- X Lower Bound Fit - The X-value corresponding to the beginning of the fit.
- X Upper Bound Fit - The X-value corresponding to the end of the fit.
- X Lower Bound Forecast - The X-value corresponding to the beginning of the forecast.
- X Upper Bound Forecast - The X-value corresponding to the end of the forecast.
- R2 - The R2 value of the regression.