Curve fit theory
Generally, curve fit algorithms determine the best-fit parameters by minimizing a chosen merit function. To optimize the merit function, you must select a set of initial parameter estimates and then iteratively refine the merit parameters until the merit function does not change significantly between iterations. The Levenberg-Marquardt algorithm has been used for nonlinear least squares calculations in the current implementation.
The goodness of fit is shown as an R2-value. A value of
R2=1.0 indicates a perfect fit, whereas
R2=0.0 indicates that the regression model might be
unsuitable for this type of data.
R2
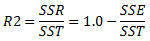
where
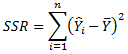 (the regression sum of
squares)
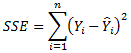 (the residual or error sum
of squares)
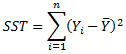 (the total sum of squares,
SST= SSE+SSR)
and
 represents the
ith fitted value (calculated using the selected model) of the
dependent variable Y.
Limitations to curve fitting
Because the calculation of the curve is an iterative process, the calculation must stop somewhere. In some cases, the maximum number of iterations might be reached before the best possible curve has been calculated. In that case, a message on the title bar of the visualization will inform you of this. In some cases, for example, if the data is widely scattered or too few data points are available, the iterative process might also result in a curve that converges on a false minimum.
When a model is applied during data analysis, it is important not only to look at the R2-value and how well the curve fits the current markers in the scatter plot, but also to consider what the curve would look like for more extreme values and determine whether the model is reasonable in a scientific or statistical context. The number of unique x-values must be larger than, or equal to, the number of degrees of freedom to obtain a unique curve. If the curve can be solved in an infinite number of ways, it is not certain that the presented curve will be relevant to your data.
General references
Heath, M.T., (2002), Scientific Computing: An Introductory Survey, 2nd ed., McGraw-Hill, New York.
Anderson, E., Bai, Z., Bischof, C., Blackford, S., Demmel, J., Dongarra, J., Du Croz, J., Greenbaum, A., Hammarling, S., McKenney, A., Sorensen, D., (1999), LAPACK Users' Guide, 3rd ed., Society for Industrial and Applied Mathematics, Philadelphia, PA, ISBN = 0-89871-447-8
References for Holt-Winters forecast
Rob J Hyndman and George Athanasopoulos (2013), Forecasting: principles and practice. http://otests.com/fpp/7/1.
Rob J. Hyndman, Anne B Koehler, J. Keith Ord, and Ralph D. Snyder (2008), Forecasting with Exponential Smoothing: the state space approach, Springer.